Mashkanta Refinancing Israel: When and How to Renegotiate
Mihzur Mashkanta: Refinancing in Israel
Mihzur Mashkanta (מיחזור משכנתא) is the process of refinancing your mortgage in Israel. It involves replacing your existing mashkanta with a new loan, usually from another bank, under more favorable conditions. This is similar to loan renegotiation in France.
Refinancing is relevant in three situations: when market rates have dropped significantly since you took out your loan (rate savings), when your personal situation has changed (for example, moving from non-resident to resident/Oleh, which opens up preferential conditions), or when your loan structure is suboptimal and can be improved.
For buyers from abroad who took out their mashkanta under non-resident conditions and have since made Aliyah, refinancing is almost always advantageous: switching to the resident scale can reduce the rate by 0.5 to 1.5 points and increase the LTV from 50% to 75%.
When to Refinance: The 3 Triggers
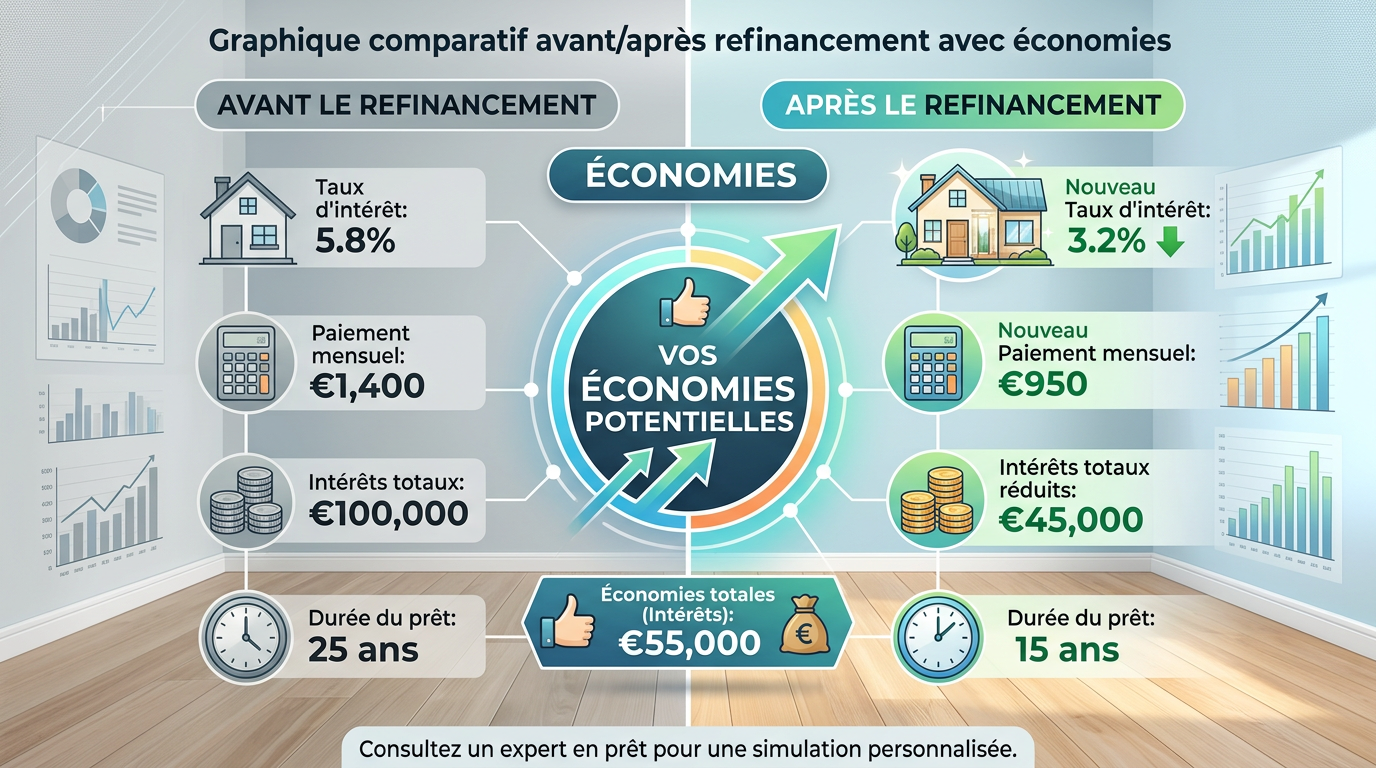
Trigger 1 — Rate Drop: If market rates have fallen by 0.5 points or more since you took out your loan, refinancing becomes worthwhile. On a loan of ₪1,000,000 over 15 years, a 0.5-point drop represents a savings of ₪25,000 to ₪40,000 over the remaining term.
Trigger 2 — Status Change: Moving from non-resident to Israeli resident (Alyah) is the most powerful trigger. Resident conditions are significantly more favorable: 75% LTV (possibility to release equity), preferential rates, and access to options not available to non-residents.
Trigger 3 — Track Optimization: Even without a rate drop, restructuring your tracks can reduce the total cost. For example, replacing an inflation-indexed fixed track (Tsamous) that is heavily penalized by inflation with a non-indexed fixed track.
The step-by-step refinancing process
Refinancing follows a 5-step process. Your broker analyzes your current mashkanta and identifies potential savings. They approach 3-5 competing banks with your updated file. You receive comparative offers and choose the best one. The new bank repays the old mashkanta and registers its own mortgage at the Tabo. Refinancing fees (valuation 2,000-3,000₪, application fee 0.25%, Tabo fee 500₪) are deducted from the new loan.
The total timeframe is 4 to 8 weeks, similar to a first mashkanta. From abroad, your lawyer and your broker handle the entire process via power of attorney.
Refinancing Costs and Break-Even Point
Refinancing is not always profitable. Costs to consider include: early repayment penalties (Amla) on existing fixed-rate tracks (0% to 5% of the repaid principal, depending on the difference with the market rate), new bank application fees (0.25% of the amount), property appraisal (2,000₪ to 3,000₪), Tabo registration fees (500₪), and broker commission (0.5% of the new amount).
As a general rule, refinancing is worthwhile if the total savings over the remaining period exceed 150% of the operation's cost. Your broker will calculate this threshold precisely before starting the process.
Special Case: Refinancing After Alyah
The most common scenario among IsraelStart clients: you purchased from abroad with a non-resident mashkanta (LTV 50%, rate 5.5%), then you make your Alyah 2 years later. Refinancing at the resident rate gives you an LTV of 75% (possibility to withdraw capital for a second purchase), a reduced rate by 0.5 to 1 point, and access to special Oleh conditions.
The total savings over 15 years can reach ₪80,000 to ₪150,000 — a gain that more than justifies the costs of the operation. The IsraelStart turnkey support includes post-Alyah follow-up and coordination of the refinancing.
Optimal Timing for Refinancing: Key Indicators to Watch
To determine the right moment to refinance, monitor three main indicators. The Bank of Israel's base rate: a decrease of 0.25 points or more justifies a reassessment. Promotional offers from competing banks: at the beginning and end of the year, banks often propose preferential conditions to attract new clients. And the change from non-resident to resident status: this is the most impactful trigger, often making refinancing almost automatic.
Your mashkanta broker can set up proactive monitoring of these indicators and alert you when a refinancing opportunity arises. This service is part of the ongoing support offered by IsraelStart partners for clients abroad.
Key Points to Remember
For buyers from abroad, the main takeaways on this topic are as follows. The involvement of a specialized lawyer is essential to secure every aspect of your transaction. Administrative processing times in Israel generally range from 2 to 6 weeks for standard procedures, but may be longer for non-residents. All documentation must be carefully prepared, translated if necessary, and comply with the specific requirements of the Israeli system.
The advantage of the turnkey support from IsraelStart is that it handles this administrative complexity: your French-speaking contact coordinates with the lawyer, broker, and authorities, freeing you from the language barrier and Hebrew-language procedures.
Testimonial and Feedback
Buyers supported by IsraelStart for this type of transaction consistently report two major benefits. First, time savings: without guidance, procedures from abroad take 2 to 3 times longer due to back-and-forth, language misunderstandings, and missing documents. Second, security: the expertise of our lawyers and brokers prevents costly mistakes that, once made, are difficult and expensive to fix.
Our philosophy is simple: every technical aspect of real estate acquisition in Israel must be handled by a professional, so that buyers from abroad can focus on what matters most — choosing the right property, at the right price, in the right city.
Need personalized support?
An IsraelStart expert will call you within 24h with a personalized analysis of your project.



